Mark, a former law enforcement officer based in Florida, began his real estate investment journey without a high income, never exceeding ,000 annually. Despite this, he managed to build a substantial portfolio of 25 rental units in less than five years, eventually retiring from his primary job at the age of 50. A crucial element in his initial success was leveraging the equity in his own home.
To fund his first investment—a single-family home in Virginia's Shenandoah Valley valued at 0,000—Mark utilized a Home Equity Line of Credit (HELOC) against his fully paid-off primary residence. Although his home was worth approximately 0,000, he strategically opted for a ,000 HELOC, roughly 15% of his home's value. This allowed him to finance the investment without overextending his home's equity.
Similarly, Michigan-based investor Scott Steenbergh and his wife tapped into their home equity to purchase their first sober-living rental property. Given that investment properties often demand higher down payments, a HELOC provided the necessary capital. Steenbergh noted that this allowed them to "put existing equity to work" without needing to sell their current home.
A HELOC enables homeowners to borrow against the equity they have accumulated in their property—the difference between its market value and the outstanding mortgage balance. Unlike a traditional home equity loan, which provides a lump sum, a HELOC operates like a revolving credit line, offering flexibility to draw funds as needed during a specified "draw period."
During the draw period, funds can typically be accessed via checks or a linked credit card. Once borrowing commences, minimum monthly payments are required, often with options for interest-only payments during this phase. The amount one can borrow is determined by factors such as the lender's policies, the home's value, existing debt, and the borrower's financial standing. Mark's decision to take out a ,000 HELOC, despite being eligible for more, exemplifies a cautious approach to align with his investment strategy. Eligibility criteria generally include substantial home equity, stable income, manageable debt levels, and a favorable credit history.
HELOC funds are not restricted to home improvements; they can be used for diverse purposes, including business ventures, vacations, or medical expenses. However, a critical consideration is that a HELOC is secured by the home itself. Failure to repay can lead to restrictions on further borrowing or, in severe cases, foreclosure. Mark's strategy of using his HELOC to purchase a rental property that generated 0 in monthly profit to cover debt payments and build savings highlights a prudent use case. Steenbergh also leveraged his HELOC for a down payment, allowing him to acquire a property without liquidating his primary residence, effectively putting his equity to work.
Another investor, Kent He, employed a comparable strategy using a home equity loan, rather than a HELOC. After his San Diego home appreciated, he secured a home equity loan to invest in a short-term rental. The key difference lies in their structure: a home equity loan provides a fixed sum upfront, whereas a HELOC offers a flexible, revolving credit line. For homeowners with accumulated equity, understanding these distinctions is crucial for making informed financial decisions. As Kent He wisely put it, this offers "another tool in your tool belt" to invest wisely, provided the investment aligns with one's risk tolerance and financial goals. This approach enables homeowners to unlock capital from their homes for strategic investments, provided they carefully manage the associated risks.
Fox's Swift Roku Acquisition: Reshaping the Free Streaming Landscape
Canada's October Job Market: Unexpected Decline and Rising Unemployment
Samsung Galaxy Z Fold 8 Sees Significant Price Drop on Amazon
TP-Link Tri-Band Wi-Fi 7 Router Returns to All-Time Low Price
The Financial Strain of College Education on Middle-Class Families
SpaceX's Starlink Mobile Revolutionizes US Connectivity with Low-Band Spectrum and Next-Gen Satellites
NordVPN Basic: Secure Your Digital Life for Less Than £2 a Month
Delta Faces Fuel Cost Headwinds While Strong Passenger Demand Persists
Pope Leo XIV's Health Update and Papacy: A Comprehensive Overview
Google Home Users Report Smart Light Color Control Malfunctions
Smart Real Estate Investors Leverage HELOCs for Property Acquisition and Wealth Growth
US Weekly Jobless Claims Decline, Signaling Tight Labor Market
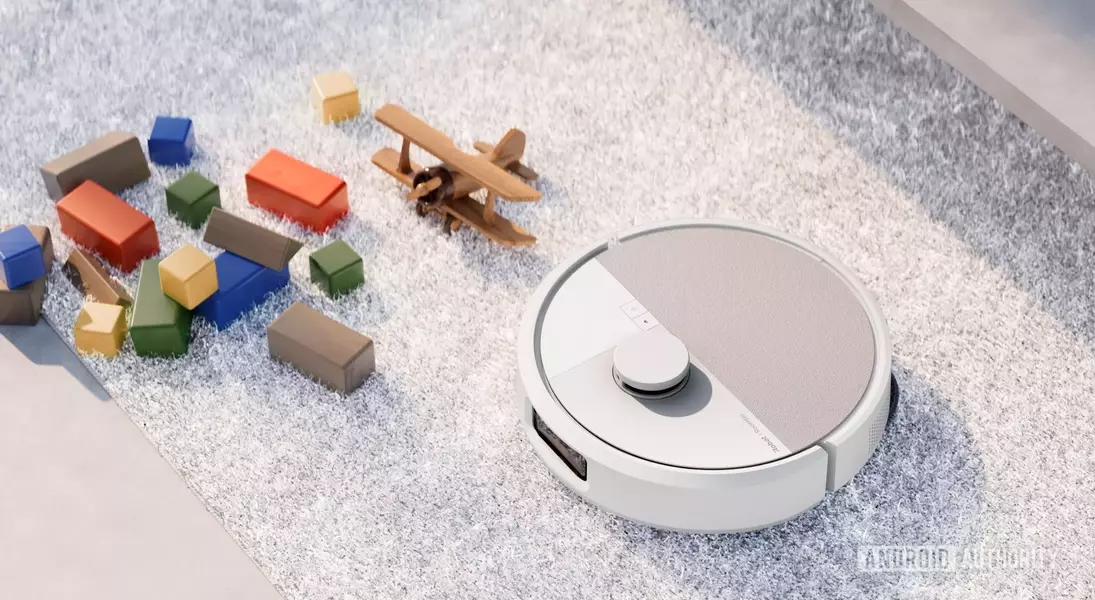
Significant Price Drop on iRobot Roomba 505 Combo at Amazon
Trump Administration Secures 0 Million in Compute Credits for AI Science Initiative
The 'Oreogate' Phenomenon: A Viral Sensation or a Clever AI Marketing Ploy?
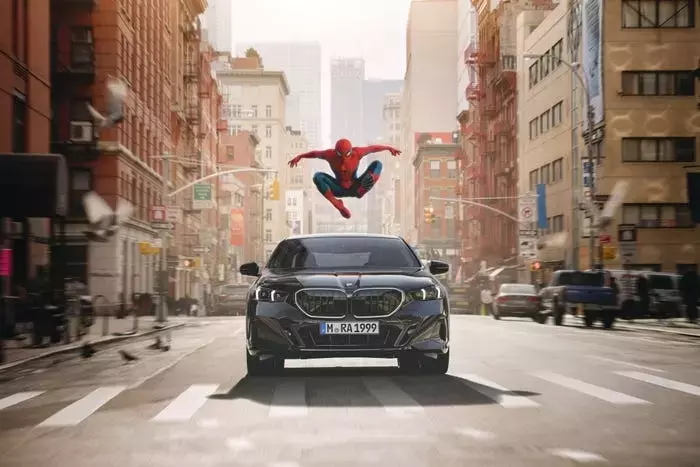
BMW's In-Car Spider-Man Ad Campaign Sparks Debate
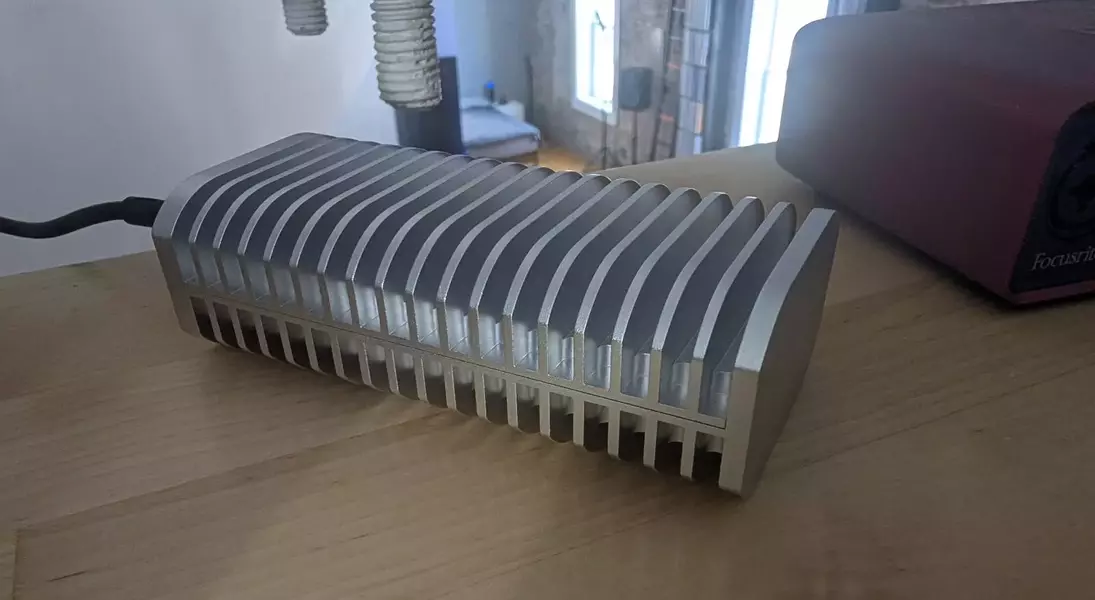
TerraMaster D1 SSD Pro: A Game Changer for Faster Rendering Speeds
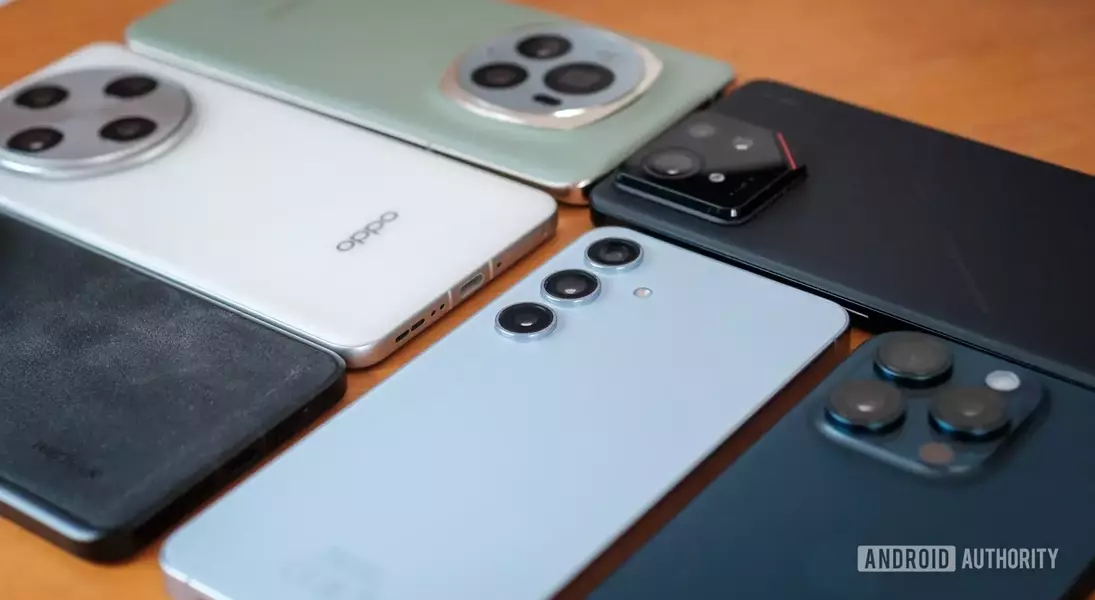
Global Smartphone Market Hits 13-Year Low, Samsung Overtakes Apple Amid Memory Crisis
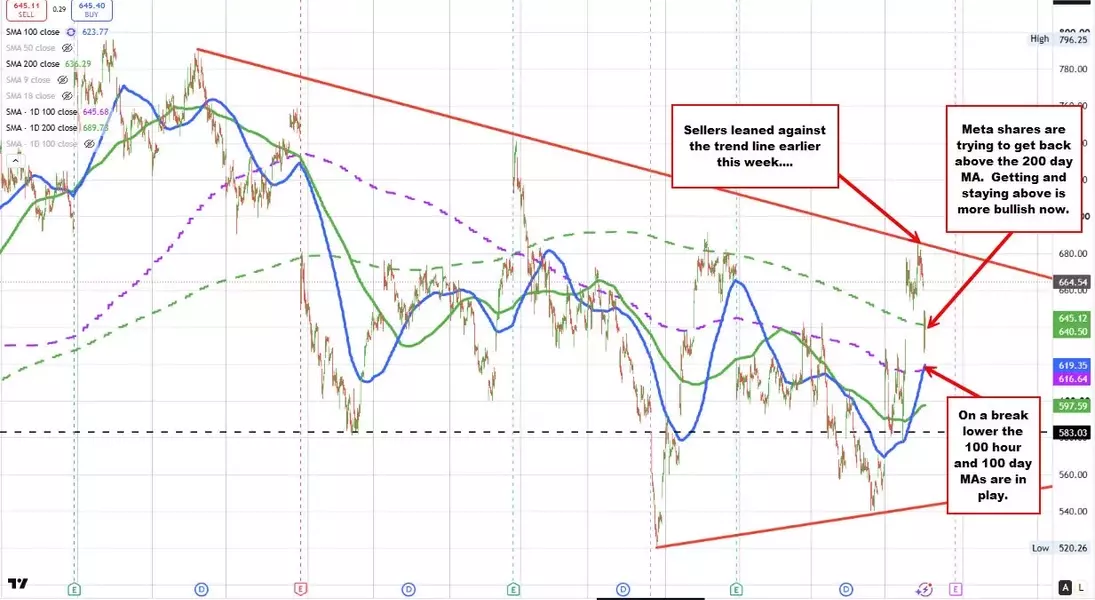
Meta Considers Multi-Billion Dollar AI Infrastructure Lease with Anthropic
Unlocking Android's Hidden Gems: Five Underrated Features for Enhanced Mobile Experience


